Home · How It Works · Case Study

Real estate investor case study

Rich found a great deal. His equity was earning exactly 0%.

Rich is a 48-year-old professional investor who saves $50,000 a year and uses real estate as his primary wealth-building vehicle. This is what changed when he stopped using his own cash for down payments, and what the numbers looked like after year one.
All figures are based on actual policy and property illustrations. Individual results will vary based on age, health, policy design, property performance, and market conditions.
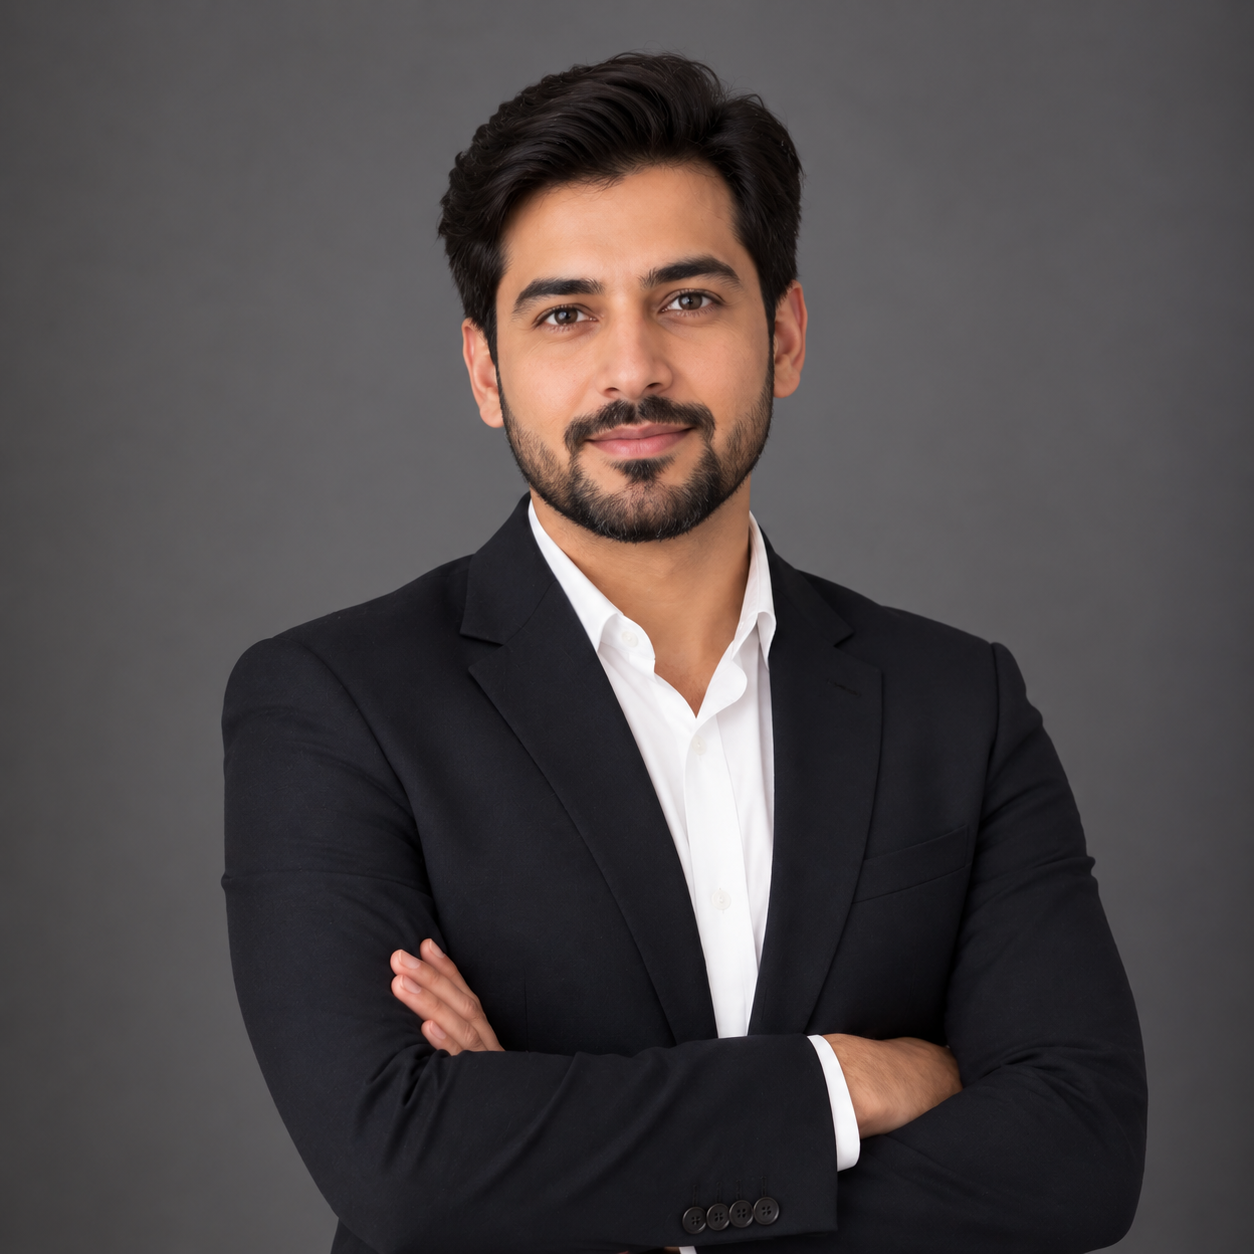
Portrait representing Rich, the real estate investor in the case study

Rich, 48

Real estate investor

Occupation Marketing Manager

  • Annual savings $50,000/yr
  • Strategy Rental real estate
  • Down payment method Own cash
  • Property target $300,000 rental
  • Challenge Capital frozen in deals
The blind spot

The deal was earning him a strong return. His equity was earning him nothing.

Rich saves $50,000 a year. After two years, he has $100,000, enough for a $60,000 down payment on a $300,000 rental property, with $40,000 remaining as reserve.

The deal pencils well. Gross rent of $2,500/month against a $1,021 mortgage payment generates strong annual income. On paper, this looks like exactly the kind of investment Rich should be making.

But there is a question nobody asks: How much is the $60,000 equity earning him?

The answer is zero. The moment Rich wires that $60,000 as a down payment, it stops working. It is frozen inside the property until he refinances or sells. The deal grows. His capital does not. He is running one engine when he could be running two.

"Your deal is earning you X%. Your equity is earning you 0%. Both cannot be true at the same time, unless you change the process."

The traditional approach

  • Purchase price $300,000
  • Cash down payment $60,000
  • Mortgage $240,000
  • Gross monthly rent $2,500
  • Mortgage payment $1,021
  • Annual rental income $17,748
  • Cash-on-cash return 29.58%
  • Equity growth rate 0%
The IBC approach

Rich deposits $50,000/year into a whole life policy instead. Here is what Year 2 looks like.

Rather than saving cash in a bank account and wiring it as a down payment, Rich deposits his annual $50,000 into a participating dividend-paying whole life policy, structured for maximum cash value growth. By Year 2, the policy has grown enough to fund the down payment through a policy loan. His cash value keeps compounding. The loan sits separately. The death benefit, not the property, serves as collateral.

Year 2 policy snapshot

What Rich's policy looks like

  • Annual deposit $50,000
  • Total cash value $84,147
  • Growth rate Daily compounding
  • Total death benefit $913,060
  • Policy loan available $75,732
  • Loan used for down payment $60,000

The deal, same as before

Same property. Different capital source.

  • Purchase price $300,000
  • Policy loan (down payment) $60,000 @ 6.2%
  • Annual loan interest $3,720
  • Collateral Death benefit
  • Rich controls repayment Yes
  • $84,147 cash value during loan Still growing daily
  • Gross cash-on-cash return 477.10%
Cash-on-cash return calculated on net cash deployed from personal funds after policy loan. Policy loan interest of $3,720/yr is cost of capital. Individual results depend on policy design, insurer, and property performance. These figures are for illustrative purposes only.
By year 3

The deal is still running. The policy grew by $56,000.

While the rental property continued generating income, Rich’s policy kept compounding on the full $84,147, as if the loan never happened. By Year 3, the policy has grown substantially, and Rich’s borrowing power has increased. He is ready to look at the next deal, with more capital than he started with.

Cash value, Year 3

$140,151

Up $56,004 from Year 2. Growing daily, uninterrupted by the outstanding loan.

Death benefit, Year 3

$1,004,018

Up $90,958 from Year 2. The policy becomes more efficient and more powerful each year.

Additional capital available

$56,004+

Above what Rich had at Year 2. Available for the next deal, or warehoused for recurring property expenses.
Side by side

The same deal. Two very different outcomes.

Rich’s objective did not change. What changed is the process he used to achieve it, and who the money was being put to work for.
Cash Down Payment
IBC Policy Loan
Down payment source
Personal savings
Policy loan against cash value
$60K equity growth during hold
0%, frozen in property
Compounding daily in policy
Who receives interest on capital
Nobody, opportunity cost
Your policy system
Collateral for down payment
The property
The death benefit
Repayment schedule
Bank's terms
Rich's terms
Cash-on-cash return (Year 1)
29.58%
477.10%
Capital available for next deal
Must save again from scratch
Policy grew, more available now
Cash-on-cash figures are illustrative based on the scenario presented. Policy loan rates, property performance, and individual results will vary. This is not financial advice.

Rich's objective didn't change. What changed is the process he used to achieve it, and who the money was being put to work for.

When Rich uses his own cash, every payment he makes is a deposit into someone else’s bank. When he uses a policy loan, the interest stays in his system. The deal is identical. The capital outcome is not.

Let's model this against your actual portfolio.

In a free 30-minute call, JinJin will walk through your current deal structure and show you exactly how much capital you have been leaving on the table, and what a different process could recover.